You’re Not Alone
Falling behind on your mortgage is stressful — but you may have more options than you think, and time matters.
The earlier you reach out to your lender and the right professionals, the more choices you’re likely to have.
Know Your Options
Options to Explore
Every situation is different. These are common paths homeowners discuss with their lender, a real estate attorney or a HUD-approved housing counselor. Not every option is available to everyone.
Talk to Your Lender / Loan Modification
Your lender may be able to change the terms of your loan, such as the payment, rate or length, to make it more affordable. Ask your servicer what loss mitigation options they offer.
Repayment Plan or Forbearance
A repayment plan spreads missed payments over time. Forbearance temporarily pauses or lowers payments during a short-term hardship. Both depend on your lender’s approval.
Refinance
If you have equity and qualify, a new loan could pay off the current one. Missed payments can make this harder, so it’s worth asking a mortgage professional early.
Traditional Sale (If You Have Equity)
If your home is worth more than you owe, selling before a foreclosure sale may let you pay off the loan and keep any remaining proceeds. This is where I can help most directly.
Short Sale
If you owe more than the home is worth, your lender may agree to accept less than the full balance. Short sales need lender approval and can take time, so starting early helps.
Deed in Lieu of Foreclosure
You voluntarily transfer the home to your lender in exchange for release from the loan, if the lender agrees. Terms vary, so review them carefully with an attorney.
How I Can Help
Clear Information, Calm Guidance
If selling turns out to be part of your plan, I’ll help you move forward thoughtfully and on a schedule that works for your situation.
Free Foreclosure Guide
Know Your Options, Step by Step
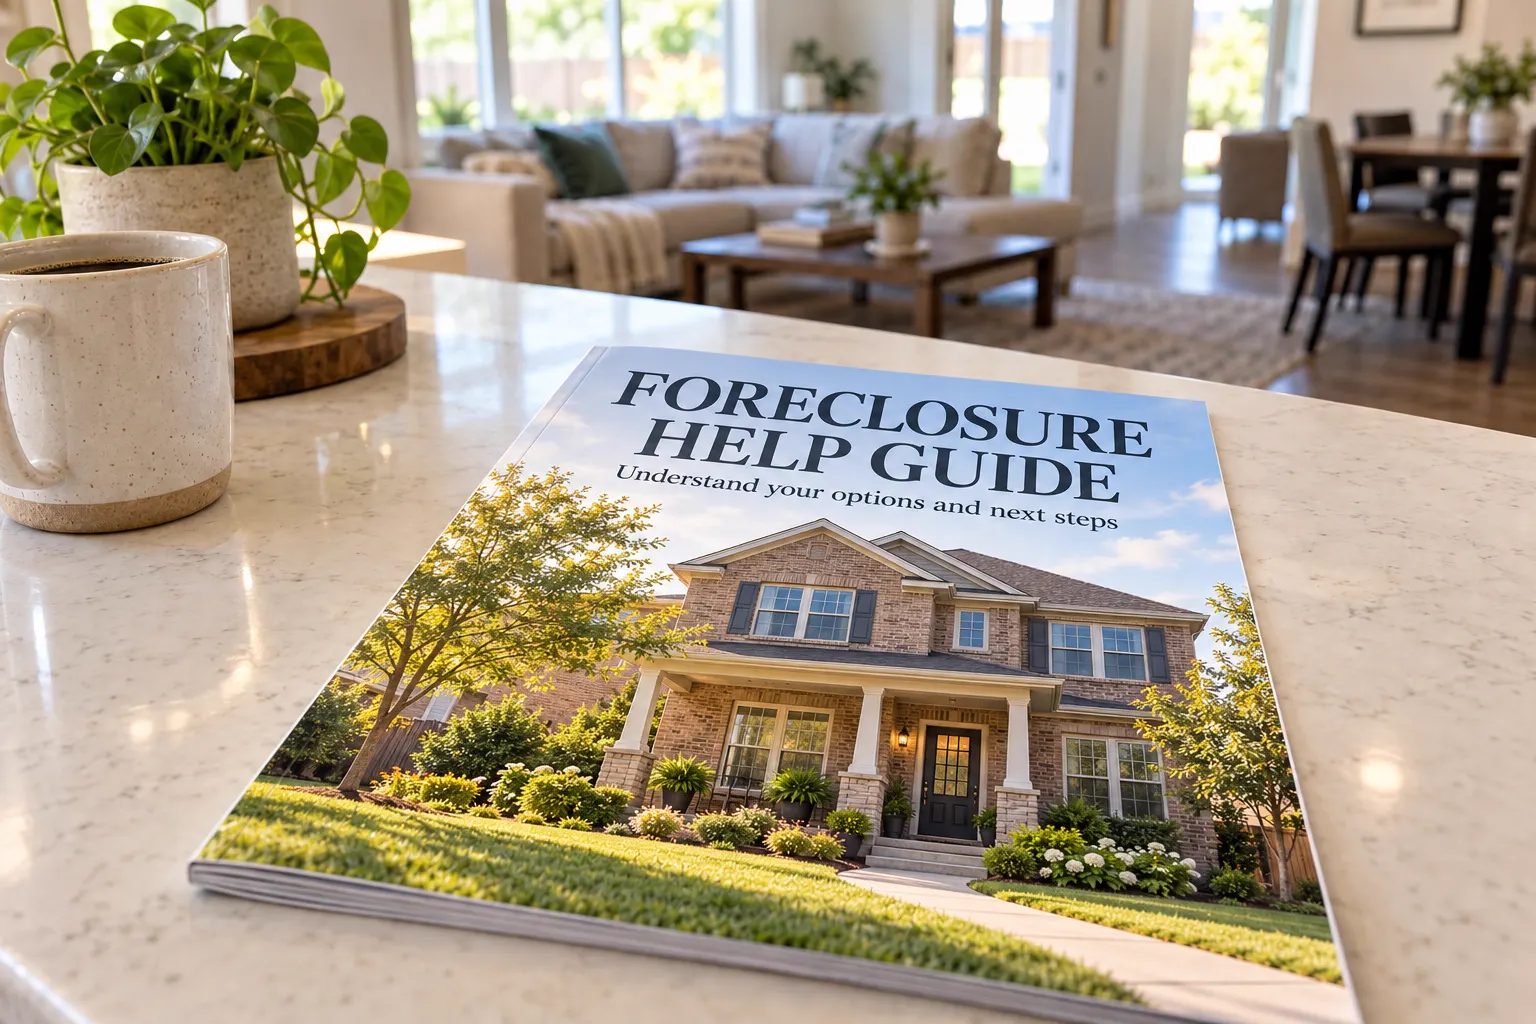
Download the free Foreclosure Help Guide for a clear, private overview of where you stand and what to ask next.
- How the foreclosure process and timeline generally work in Texas.
- Common options to discuss with your lender, attorney or a HUD-approved housing counselor.
- Questions to ask before a sale date is set.
- A simple checklist for organizing your documents and next steps.
Schedule a Private Consultation
Take the First Step Today
Pick a time for a free, private conversation by phone or in person. We’ll talk through your situation at your pace, and you’ll leave with a clearer picture of your choices and next steps.
Choose a date and time that works best for you.
Your information stays confidential. I only use what you share to contact you about your situation, and I won’t share it with anyone without your permission.
Why Work With Me
Compassionate, Discreet and Judgment-Free
Life happens: job changes, medical bills, divorce, a loss in the family. Whatever brought you here, you deserve to be treated with respect. I’ll listen first, explain things in plain language and help you make the decision that’s right for you.
- No judgment, no pressure, just honest answers about your home and the market.
- Discreet communication, handled the way you prefer: call, text or email.
- Local market knowledge across Greater Houston to price your home realistically.
- Teamwork with your lender, attorney and housing counselor, not around them.
Next Steps
What Happens Next
Here’s what working together looks like if you decide to reach out. You stay in control of every decision.
Foreclosure FAQs
Answers to Common Questions
How long does foreclosure take in Texas?
Timelines vary, and they can be shorter than many people expect. Most Texas foreclosures are handled outside of court, which can move quickly once the required notices are sent. Because every loan and situation is different, the best thing you can do is act early: contact your lender, and talk with a real estate attorney about your specific deadlines.
Will a short sale hurt my credit?
A short sale is generally reported on your credit, but the impact depends on your overall credit history and how the lender reports it. Some people find it less damaging than a completed foreclosure, but that isn’t guaranteed. A HUD-approved housing counselor or financial professional can help you understand how each option may affect you.
Can I sell my home if I owe more than it’s worth?
Possibly. A short sale lets you sell for less than you owe if your lender approves it. The lender will usually ask for financial documents and a hardship explanation. You may also want to ask an attorney or tax professional whether any remaining balance could be pursued or treated as taxable income.
Is it too late if a foreclosure sale date is already scheduled?
Not necessarily, but time is very short. Contact your lender and a real estate attorney right away. In some cases a sale may still be possible before the scheduled date, depending on your lender and your circumstances.
Does it cost anything to talk to you?
No. An initial consultation with me is free and there’s no obligation. If you decide to sell, we’ll talk openly about how I’m paid before you sign anything. HUD-approved housing counselors also generally offer free or low-cost help.
Will my neighbors know about my situation?
Your conversations with me are private. If you choose to sell, your home is marketed like any other listing, and I won’t share details about your finances or circumstances with buyers or anyone else without your permission.
Important: I’m a licensed real estate agent, not an attorney, tax professional or financial advisor. The information on this page is general and is not legal, tax or financial advice. Foreclosure rules and timelines depend on your loan and circumstances. Please consult a real estate attorney, a HUD-approved housing counselor and, where appropriate, a tax professional about your specific situation. No outcome can be guaranteed.
You Don’t Have to Figure This Out Alone
The sooner we talk, the more options you may have. Schedule a free, confidential consultation and let’s look at your situation together.